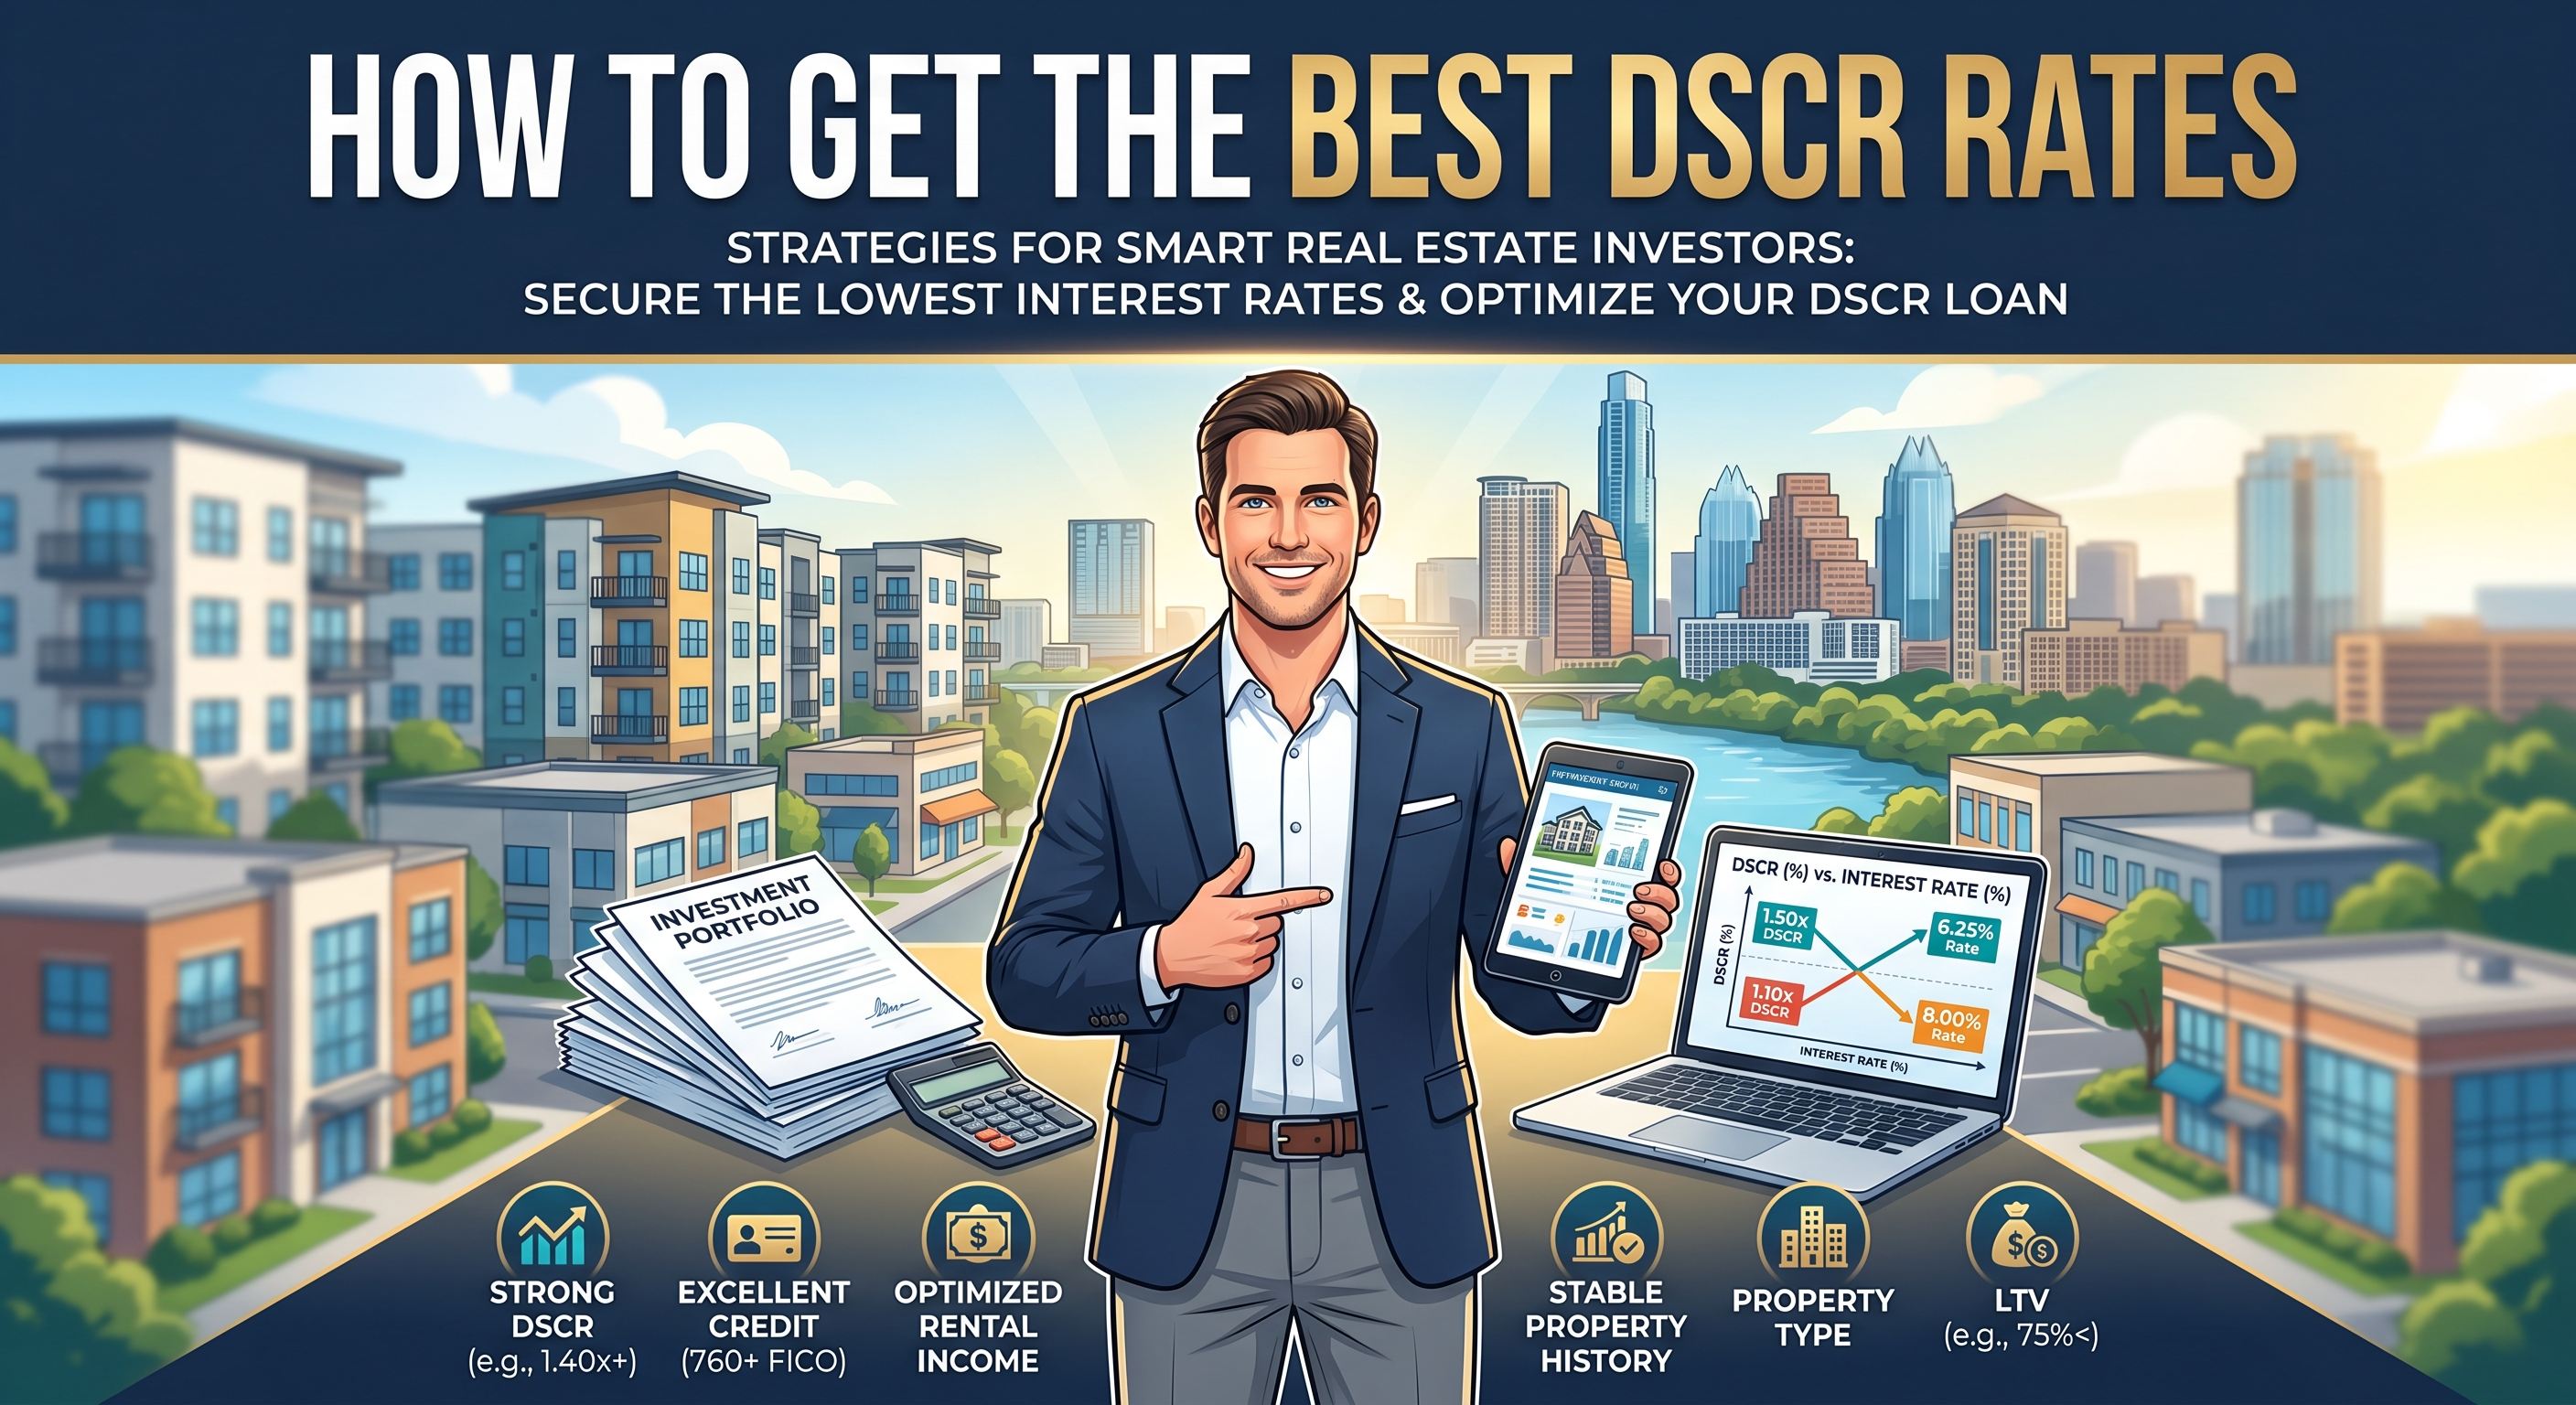
Mastering DSCR: Your Guide to Securing the Best DSCR Rates.

Learn how DSCR loans work so you can secure the best rates. .

How to Get the Best DSCR Rates

For real estate investors looking to scale their portfolios, Debt Service Coverage Ratio (DSCR) loans are one of the most powerful tools available. Because qualification relies on property cash flow rather than personal tax returns, W-2s, or personal Debt-to-Income (DTI) ratios, investors can secure financing without hitting traditional lending caps.

However, because DSCR loans carry a unique pricing structure, interest rates can vary significantly depending on how you structure your deal. Below is a complete guide on how DSCR pricing works and what steps you can take to land the lowest available rate.

What Determines Your DSCR Rate?

Unlike traditional mortgages with fixed rate matrices, DSCR loans use risk-based pricing. Lenders look at key metrics to calculate the deal's overall risk profile:

  1. Debt Service Coverage Ratio (DSCR): Calculated as Gross Monthly Rental Income / Monthly PITIA (Principal, Interest, Taxes, Insurance, and HOA). A ratio of 1.0 means the property breaks even. Ratios above 1.20 to 1.25 unlock the lowest interest rate tiers.
  2. Loan-to-Value (LTV) / Down Payment: Lower leverage means lower risk for the lender. Putting down 25% to 30% (70%–75% LTV) yields better rates than maxing out leverage at 80% LTV.
  3. Credit Score (FICO): Even though personal income isn't verified, credit scores still influence rate adjustments. Scores of 740+ secure top-tier pricing, while scores below 680 face noticeable rate add-ons.
  4. Prepayment Penalty Structure: Accepting a 3-year or 5-year step-down prepayment penalty (e.g., 5/4/3/2/1) typically reduces your interest rate compared to a zero-penalty option.
  5. Property & Rent Type: Long-term single-family rentals (SFRs) generally qualify for lower pricing than 2–4 unit properties or short-term rentals (Airbnb/VRBO).

5 Practical Steps to Lock in the Lowest DSCR Rate

LeverStrategyRate Impact
Increase DSCRAim for a ratio above 1.25 (raise rents or lower property insurance).Unlocks top pricing tiers
Lower LTVPut down 25%+ instead of the minimum 20%.Eliminates leverage adjustments
Optimize PrepaymentChoose a 3-year or 5-year prepayment penalty structure.Lowers interest rate by 0.25% to 0.75%
Boost Credit TierTarget a 740+ FICO before applying.Cuts interest rates significantly vs. <680
Buy Down the RateUse upfront discount points if planning a long-term hold.Directly buys down the note rate

Example: Comparing Your Scenario Options

To visualize how different loan parameters impact interest rates and monthly cash flow, explore the scenario model below:

Get Expert Guidance on Your DSCR Deal

Navigating investor guidelines requires direct access to aggressive Wholesale Non-QM matrices. For custom rate quotes and deal structuring, visit www.dscr-loan.ai or contact:

Matt M Dean

NEXA Lending

Phone: 512-415-6142
Let us help you!

Our representative will be in touch with you.

* Specific loan program availability and requirements may vary. Please get in touch with your mortgage advisor for more information.